Badminton Betting Tips 2026: How to Build a Price, Read a Margin, and Avoid Paying for a Promise
 Available in US
Current as of October 30, 2026 · verified against the Gambling Commission’s public register.
Badminton sits in an awkward place on a UK bookmaker’s site. The sport is global, deeply structured, and decisively second-tier in the betting volume behind football, horse racing and tennis — which means the betting menu at most licensed operators is short, the in-play markets thinner than for the bigger sports, and the marketing copy that hangs around it thinner still. That is also why this guide treats badminton betting as the cost problem it really is: the punter who walks in unprepared pays for the sport’s obscurity in the form of a wider margin, a stingier bet builder and a bonus whose wagering requirement does most of the work the marketing glosses over. The job of the next several thousand words is to make those costs visible, name what is and is not documented, and lay out a working method for reading a price before it is taken.
A note on what this page is and is not. It is not a tip sheet and it does not pretend to know who will win the All England Open, the Thomas Cup or the next BWF World Championships. No model of past form, no head-to-head ledger, and no amount of reading the draw will turn a guide into a forecast, and any site that tells a reader otherwise is selling certainty that does not exist. What a guide can do is show how a price is built, where the bookmaker’s margin hides inside it, why a tip is only a probability dressed up, and what the difference between a value bet and a long shot on a thin market looks like when the margin is wide. That is the material.
Badminton: How the Sport Shapes What Gets Bet On
The Badminton World Federation is the governing body for international badminton, founded in 1934 as the International Badminton Federation. It runs the BWF World Tour, the World Championships, the Thomas Cup and Uber Cup for men’s and women’s national teams, the Sudirman Cup for mixed national teams and the All England Open, first held in 1900 and still one of the sport’s most prestigious individual events. The Olympics have included badminton since 1992 and mixed doubles since 1996. None of this history is a betting tip. It is the calendar the markets hang from, and a punter who bets on a tournament without knowing the format and the schedule is gambling on the sport’s name rather than its contests.
The match format is one of the cleanest in racquet sport and one of the most punishing to misread. Each game is played to 21 points under rally point scoring — a point is scored on every rally, regardless of who served — and a match is the best of three games. At 20–20 a side must lead by two to win, and at 29–29 the next point takes the game. The five disciplines are men’s singles, women’s singles, men’s doubles, women’s doubles and mixed doubles. A match that goes to a third game is therefore both common and decisive, which is why a match winner market is, by construction, a three-game market: a 2–0 lead is not the same proposition as a 2–1 win, and a price that flattens the two is asking the punter to take a discount the form book does not support.
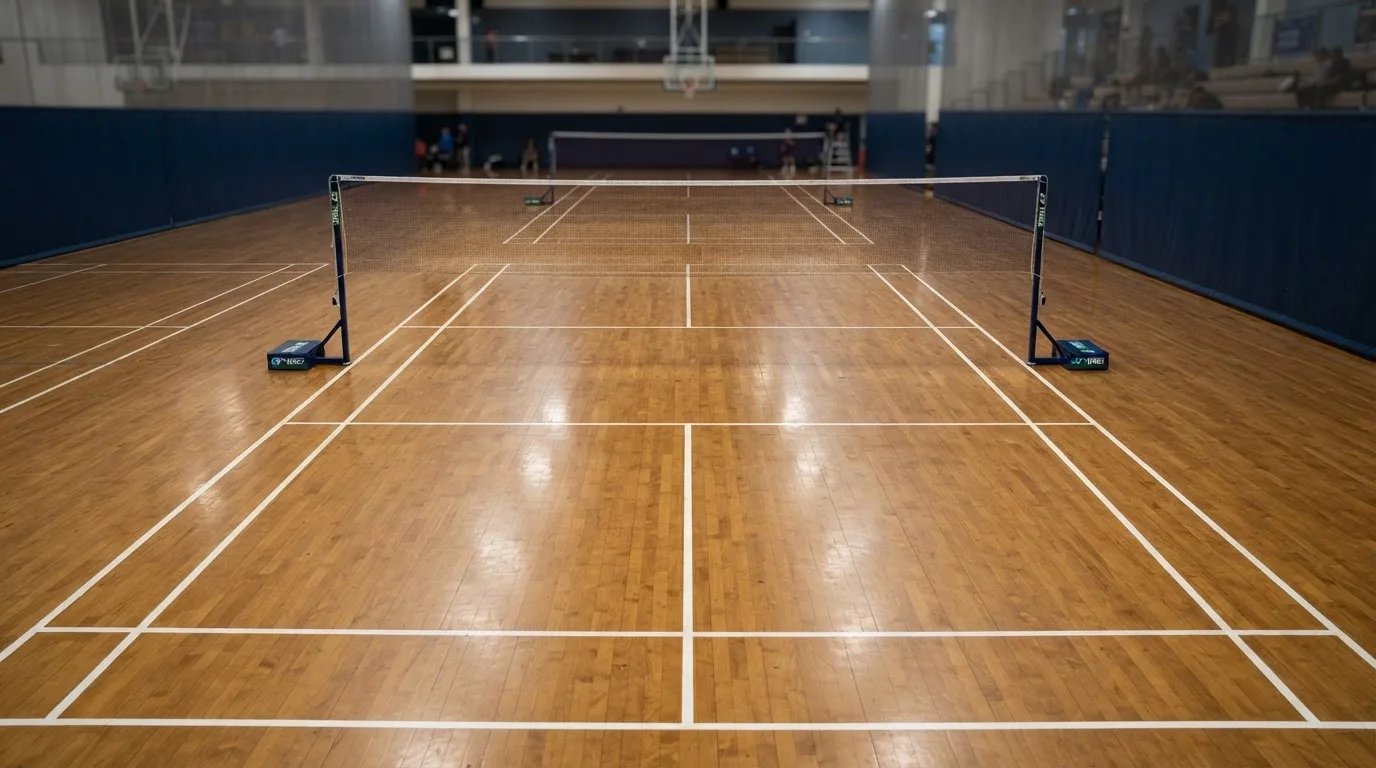
A court is 13.4 metres long, 6.1 metres wide for doubles and 5.18 metres wide for singles, with the net at 1.55 metres at the edges and 1.524 metres at the centre. The numbers do not matter to a bettor in themselves. They matter because they bound the sport: there is no ball, no pitch, no weather to read, and there is no team shape in the football sense. The variable that decides a badminton match is the player — form, fitness, recent minutes, head-to-head, surface (the All England’s boards play slower than the Asian Opens), the tournament round — and the variable that decides a badminton betting market is how few bookmakers price that player at all.
Badminton Betting Sites in the UK: What “Licensed” Actually Means
Every brand that takes a bet from a customer in Great Britain from a remote channel needs a Gambling Commission licence, regardless of where the operator is based — a Curaçao, Maltese or Gibraltar licence does not substitute. The Commission is a non-departmental public body sponsored by the Department for Culture, Media and Sport, and it licenses commercial gambling under the Gambling Act 2005. The Act covers England, Scotland and Wales; Northern Ireland sits under older law, so the honest phrase is “Great Britain licence” or “GB-licensed”, never that a GB licence covers Northern Ireland.
A Commission licence comes in categories. The one a sportsbook needs to offer bets on real sporting events is remote general betting standard (real events); a betting exchange runs under remote betting intermediary; pool betting has its own licence. A site can be licensed for several categories at once and several brands can run under one licence — Ladbrokes and Coral under LC International, for example — which is why two familiar brand names on a register page can sit under one company number. The Commission’s public register is searchable by business name, trading name, domain or account number, and the register entry is the whole test of who holds what. Quote no count of licensed operators without the access date; the page changes week to week.
The verification point a bettor notices is the one the law made mandatory. Since 7 May 2019, name, address and date of birth are checked before a customer can deposit or gamble — including with a free bet or bonus — so there is no anonymous play at a licensed site. The check is not optional, and a bookmaker that does not ask for it is not the bookmaker it claims to be. The transfer of personal data is the price of the consumer protections that come with the licence: GAMSTOP membership, the 10x wagering cap on bonuses, the £150 financial-vulnerability trigger, and a route to the Commission if a complaint goes nowhere.
The set this guide writes about is the ten operators the Commission’s register places in this ranking. Each is reviewed below with what its own terms page says about the subject of this guide, and with the verdict the specifications above it do not make for the reader. A reader looking for a site outside this set has a single, honest route: the Commission’s own register, checked before the first deposit, with the brand name typed into the search box.
The Operator Set at a Glance
| Brand | Gambling Commission account | Licence holder | What the operator’s own terms state on badminton |
|---|---|---|---|
| Ladbrokes | 54743 | LC International Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Copybet | 53774 | Copybet UK Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| BoyleSports | 39469 | Boylesports Enterprise | Markets and offers described on its sports pages; terms govern each promotion and each market |
| BetTom | 64959 | Bet Tom Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Tote | 54779 | TDCO Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Swifty Sports | 58957 | Swifty Global (UK) Ltd | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Fitzdares | 400 | Fitzdares Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Betmaster | 65699 | BM Solutions GB Ltd | Markets and offers described on its sports pages; terms govern each promotion and each market |
| Bet600 | 44731 | Tyche Tech Limited | Markets and offers described on its sports pages; terms govern each promotion and each market |
| bet365 | 55148 | Hillside (UK Sports) ENC | Markets and offers described on its sports pages; terms govern each promotion and each market |
The licence lines are the floor: every brand above holds a Commission licence and is a member of GAMSTOP, and every customer at any of them will be verified before the first deposit. The “what the operator’s own terms state” column is intentionally identical across the ten rows because the page has no verified copy of any of these operators’ badminton-specific market rules — the match winner, handicap, total games and outright markets each operator offers, the suspension rules, the void rules, the settlement timing. That is not a small gap on a guide about badminton betting. A reader who bets on a tennis-style match winner market expecting the same settlement at every operator will find the operators do not agree on what counts as a retired player, a walkover, a retirements-after-the-second-game case. The way to close the gap is the operator’s own rules page for the market in question, read before the bet is placed.
How to Read a Badminton Price: Margin, Value and What the Tip Actually Means
The bookmaker’s margin is the cut taken from every unit bet on a market, and on a two-way match winner it sits hidden in the gap between the implied probabilities. Take an illustrative example — not a quoted price, only the shape of one. Two players are priced at decimal odds 1.90 and 1.90 for a match winner. The implied probability of either outcome is 1/1.90, or 52.6%, and the two together imply 105.3% of the market, which is more than 100%. The excess — that 5.3 percentage points — is the bookmaker’s margin, and the punter’s payment for the privilege of taking the price. The payout share is 100% minus the margin, here about 94.7% of every pound staked across both outcomes in the long run.
A margin is not the same thing as a fee. A fee is taken out of a stake or a winning return and shows up as a line on the betting slip; a margin is taken out of every price and shows up as the gap between probabilities and certainty. The punter who backs the favourite at 1.90 has not paid 5% to the bookmaker in a line item; the punter has accepted a price whose implied probability is 5.3 points higher than the actual probability of winning, and the bookmaker earns the difference across all bets. The two descriptions say the same thing in different words, and the second one is the one a guide writes because it is the one a betting slip will not.
Real badminton markets are rarely priced at the 1.90/1.90 illustration above. The bigger the price difference between the two players — Viktor Axelsen at 1.20 against a qualifier at 5.50, for instance — the more the margin concentrates on the favourite, and a thin second-tier event prices differently to a BWF World Tour final because fewer operators post a line and the one that does takes a wider cut to manage its exposure. The number changes. The principle does not: every price on every market carries a margin, and the punter who never asks what the margin is pays whatever it is.
A value bet, in the sense the term carries in any guide, is a price whose implied probability is lower than the punter’s own estimate of the probability of the outcome. If the punter judges the favourite to win 70% of the time and the price implies 52.6%, the price is value, even though the favourite is overwhelmingly expected to win. At 55%, the price is marginal — there is a margin of 2.4 percentage points of expected value, which the variance of singles badminton will eat on most nights. At 50%, it is a loss, and betting it because ‘Axelsen always wins’ is paying the bookmaker for the privilege of being wrong more often than the punter thinks.
That is also why no tip is ever certain. A tip is a probability dressed as a name, and a price is the bookmaker’s probability dressed as a return. The two have to be compared on the same scale — the punter’s probability versus the price’s probability — and the comparison is always uncertain because the punter’s probability is a guess at best. Form, head-to-head, recent minutes, surface, tournament round and the draw are the inputs. None of them is decisive, all of them are noisy, and the noise is what the margin charges for. A punter who treats a tip as a forecast rather than a probability is the punter the margin was built to tax.
What a Bonus Actually Costs: Wagering, Minimum Prices and Deadlines
The marketing word is “free”. The terms word is “wagering requirement”, and on every UK-licensed site the wagering requirement is capped at 10x the bonus base since 19 January 2026. The cap means a £10 bonus at 50x wagering would have needed £500 of qualifying bets in the old regime; under the cap, no more than £100 of qualifying bets clears the bonus. The cap is a real protection — the worst offers have been pulled back inside a finite turnover — but a £100 turnover at a margin of 5% still costs the punter about £5 of expected value on a random set of bets, and the punter who clears the bonus at minimum odds 1/2 (decimal 1.50) is paying the full margin on a market that pays back less than the true price would.
A worked illustration is the cleanest way to see this. Suppose a sports welcome offer is described as half the qualifying stake back as a free bet, capped at a free-bet value of £50, with 10x wagering on the bonus base. The base is the free-bet amount, the wagering factor is 10, and the required turnover is £50 × 10 = £500. At a stake per bet of £10, that is 50 bets. Each bet, at minimum odds 1/2 (decimal 1.50), pays back £15 for a £10 stake, of which £5 is the punter’s net profit before the margin is taken into account. The total expected cost of clearing the offer — the wagering the punter must place — is the turnover multiplied by the margin of the market the punter plays. At a 5% margin on a market priced around evens, the expected cost is £500 × 5% = £25. The free bet is worth about £50 minus £25, in the roughest framing, before the free-bet rules are applied; a free bet whose stake is not returned with a win is worth less than its face value, and a free bet whose winnings are capped at a multiple of the stake is worth less still. The conclusion is the kind a guide should be honest about: the offer is real, the headline number is moderate, and the work to clear it is the price.
Two further rules the punter needs to know sit in the same terms. First, mixed-product promotions — an offer that requires play across two or more product types, such as “bet on football to get free spins” — are banned in Great Britain since 19 January 2026, and the punter who sees one is looking at an offer that should not have been shown. Second, the free bet’s stake is usually not returned with a win; a £10 free bet at odds 3.00 pays £20 in profit, not £30. The wording in the operator’s own terms is the test, and the punter who has not read it has not bet the value.
Live Badminton Betting and Cash Out: What the In-Play Market Looks Like
In-play badminton is the part of the menu where the margin is widest and the offer is thinnest. The format — games to 21, two-clear, sudden death at 29–29 — means a match can swing on a single rally inside a game, which is the kind of volatility a bookmaker prices with a wide spread because the bookmaker cannot lay off the exposure as quickly as in a football match. A pre-match price of 1.90/1.90 collapses into an in-play market in which the favourite is at 1.05 after winning it 11–4 and the outsider is at 15.00, and the punter who backs the outsider at 15.00 in play is paying a margin that can run to 15% or higher on a two-way market because the operator has fewer competing prices to discipline it.
Cash out is the bookmaker’s offer to settle a bet before the match is over, at a price the bookmaker itself sets. It is useful for cutting a loss on a bet that has gone wrong and for banking a profit on a bet that has gone right, and the price the bookmaker offers is the bookmaker’s price, with the bookmaker’s margin inside it. A punter who routinely cashes out at a small profit is, in aggregate, paying the bookmaker for the privilege of being allowed to. A punter who holds the bet to settlement pays the margin once. The two strategies are not equivalent, and the punter who has not done the arithmetic is the punter the cash-out button was designed for.
Live streaming is offered by some licensed operators for selected events and is a working tool for in-play betting on badminton only insofar as the punter can read the score faster than the operator updates the price. The score itself is publicly visible on most BWF events, which means the punter who is watching the stream is watching what every other punter with a stream is watching, and the operator is repricing the market as the score moves. There is no information advantage in the stream itself. There is, sometimes, a latency advantage — a punter watching a half-second ahead of the operator’s price update is a punter who has found an edge the market has not closed. That latency is not a documented feature of any of the operators reviewed below and is not a basis for picking one over another.
The Markets Wickets They Said They Would Cover: Match Winner, Handicap, Totals, Outrights
A match winner market on badminton is straightforward in form — back player A or player B to win the match — and treacherous in the three-game case, because a price that treats a 2–0 win and a 2–1 win as equivalent is, in effect, pricing the format. A punter looking at a price for the All England Open final has to ask whether the price is for “to win the match” or “to win in straight games”, and the difference is not a rounding error. The two markets are different markets, and they settle differently.
Handicap markets — typically expressed as a games handicap, with player A at –1.5 games and player B at +1.5 — are the cleanest way to price a three-game match, because the handicap removes the format discount from the price. A price of 1.90 on the favourite at –1.5 games is the price of winning in straight games, and a price of 1.90 on the outsider at +1.5 games is the price of winning the match or losing 2–1. The handicap is where a punter with a model of who wins the games — rather than who wins the match — finds a price.
Totals markets on badminton — over/under a number of games in the match, or over/under a total points line — are less common than match winner markets and are priced with a wider margin because fewer operators offer them. A 2.5 games line on a women’s singles match is settled at the match’s end, not in play, and the punter who takes the over is betting that the match goes to a third game. The volatility of the format — a 21–19 third game is just as decisive as a 21–5 third game — means the totals market is a high-variance bet even when the price is sharp.
Outrights on tournaments are the longest-priced markets on the badminton menu, with the favourite typically priced between 3.00 and 6.00 at the start of a BWF World Tour event and the field behind. The margin on an outright market is wider than on a match market because the bookmaker cannot lay off the field exposure as cleanly, and the punter who backs an outsider at 50.1 is paying a margin that can run to 30% on a typical outright book. Outrights are also the markets where the bonus the punter is clearing will most often be placed, because the turnover requirement is large and the staking is small per bet. The arithmetic is unfavourable. The format is right. That is the trade.
A Worked Margin in Plain Prose
Take an illustrative two-way badminton match winner at decimal odds 1.90 and 1.90. The implied probability of each outcome is 1 ÷ 1.90, or roughly 52.6%. The two together imply 105.3%, which is more than the 100% a fair market would imply; the gap of about 5 percentage points is the bookmaker’s margin on the market, and the punter’s expected return across the long run of bets at these prices is about 94.7 pence for every pound staked across both outcomes. State the band — roughly 5% on a sharp two-way match winner, and somewhat wider on a thinner event — rather than the single figure, because a real market is never the illustration and a real margin is never one number across the season.
That figure is the cost of taking the price. The punter who backs the favourite at 1.90 has not paid 5% in a fee; the punter has accepted a price whose implied probability is roughly 5 points above the punter’s own estimate of the true probability, and the bookmaker earns the difference across every bet. The price is the cost, and the cost is in the price.
Responsible Gambling at a Licensed UK Bookmaker
The consumer protections that come with a Gambling Commission licence are not a courtesy. They are the law the licence enforces. GAMSTOP is the national multi-operator online self-exclusion scheme and a mandatory licence condition for online operators; the periods are six months, one year, five years, or five years with auto-renewal, and after the minimum period the exclusion stays in place for a further seven years unless the customer asks GAMSTOP to remove it. GAMSTOP covers online sites and apps. Betting shops use a separate service, and a punter who wants both has to take both steps.
Deposit limits are the punter’s own tool and a regulatory requirement the operator must offer. The first phase has applied since 31 October 2025; a second phase was postponed to 30 September 2026 and whether it is live at the moment of reading is not a question a guide can answer for the reader. The punter’s own ceiling is the punter’s own choice — there is no state-set cap on deposits or losses on sports betting — but the operator must offer one and must enforce it.
The financial vulnerability check (LCCP condition 3.4.4, in force since 30 August 2024) applies to licensed remote betting when a customer’s deposits minus withdrawals exceed £150 in a rolling 30 days. It is a public-record check (bankruptcy or county court judgments, for example), not an income check and not a credit reference check. The “affordability checks” widely reported in the press are the financial risk assessments announced in a staged plan; no start date has been published, so write “announced, staged, no start date” rather than “in force”.
Help is real and free. GamCare runs the National Gambling Helpline. GambleAware funds treatment and education. The NHS runs gambling clinics. Gamblers Anonymous runs meetings. The licensed operator’s own safer-gambling page is the route to deposit limits, product restrictions and self-exclusion. The unlicensed operator’s safer-gambling page is a marketing page without a regulatory backstop, and a punter whose self-exclusion request goes nowhere at an unlicensed site has no British route to enforce it.
Payments, Identification and the Cost of the Account Itself
The credit-card ban has been in force in Great Britain since 14 April 2020 and covers any credit-card-funded payment, including a payment routed through an e-wallet. A debit card, a bank transfer and an open-banking payment are not covered by the ban. A punter who tries to deposit with a credit card will be refused at the licensed site and the refusal is the licensed site doing its job. A punter who finds a punter that does accept a credit card has found a punter without a Great Britain licence, and the absence of the ban is the absence of the licence.
Identity verification happens before the first deposit, not after the first withdrawal. Name, address and date of birth are checked, and a punter who cannot pass the check cannot play — including with a free bet or a bonus. Source-of-funds questions at higher spend are normal under the anti-money-laundering rules, and a licensed operator asking a punter for a bank statement or a payslip at high spend is asking because the licence requires it, not because the operator is being difficult.
Whether cryptocurrency is accepted at a licensed site is not established. There is no British named-account rule and no state list of permitted payment methods that this guide can quote; the operator’s own banking page is the test, and a punter who needs a coin deposit to be allowed needs to read the banking page before signing up. A punter who walks into an unlicensed site that quotes crypto deposits has walked out of the British regulatory frame entirely, and the protections in the section above do not apply.
What an Unlicensed Site Costs
A Great Britain licence is compulsory at the point of consumption. Providing gambling facilities in Great Britain without the licence the Gambling Act 2005 requires is an offence aimed at the operator, with a sentence on summary conviction of up to 51 weeks’ imprisonment, a fine up to level 5, or both; in Scotland, up to six months. The enforcement is disruption, not blocking — cease-and-desist notices, search-engine referrals, work with registrars, hosts and payment providers — and the Commission has been given, or is about to receive, court-order DNS blocking powers. ISP blocking is not in operation as a general policy and this guide does not write that it is.
The cost to the punter is the absence of the protections a licence enforces. No GAMSTOP coverage, and a self-exclusion request that goes nowhere. No Commission complaints route, and a dispute that ends at the operator’s own decision. No approved dispute-resolution body and no British consumer redress if funds are withheld. No 10x bonus cap, and a wagering requirement that the licensed cap would have stopped. No £150 vulnerability check, and a financial situation the operator is not required to assess. The honest framing is not “safe” versus “unsafe” — both can be made to one and broken by the other. The honest framing is licensed equals checks, limits, GAMSTOP, the bonus cap and a route to the Commission, alongside verification before the first bet; unlicensed equals none of those protections and the possibility that funds are withheld with no British route to recover them.
The Ten Operators Reviewed
Each review below is a working judgement on what the operator offers a punter who bets on badminton in Great Britain. The set is the Commission’s register, not a personal ranking. Where a brand does something the others do not, the review says so. Where a brand’s offer cuts against a buyer looking for what the page’s subject is about, the review says so too.
Ladbrokes
Ladbrokes is one of the two high-street names most UK punters meet first, and the operating company is LC International Limited, which also runs Coral; the two brands are not independent operators, and a punter who holds an account with one holds the same kind of account the other offers. The Commission’s account number is 54743, with a remote general betting standard (real events) licence and a betting intermediary licence. The app offers odds boosts on horse and greyhound bets, Best Odds Guaranteed on UK and Irish horse racing, in-play betting and Acca Boosts. None of those offers is a badminton offer, and a punter who joins for the horse racing offers and expects the badminton menu to follow is joining two different books under one roof. For a badminton bettor the question is whether the match-winner menu is deep enough to be worth a £10 stake, and the honest answer is the menu depends on the week — for the All England Open it is short, for the BWF World Championships it is wider, and for the second-tier Asian Opens it is whatever the operator’s trader has priced that morning.
The verdict: a household name that prices badminton when the calendar gives it reason to, and a perfectly credible place to bet the bigger events. For a punter whose interest in badminton is a once-a-season punt on the All England final, Ladbrokes is one of the easier accounts to keep open and to fund. A punter searching for a deep in-play market every week will find the menu thin and the prices wide.
Copybet
Copybet runs under Copybet UK Limited (Commission account 53774) with a valid GB remote betting authority. The brand’s most visible offer, in the App Store listing this guide works from, is Best Odds Guaranteed all day, every day on UK and Irish racing, plus a first-past-the-post payout on horse racing even if the winner is later disqualified. As with Ladbrokes, the headline offers are racing offers, and a punter who joins for the racing is not joining for the badminton. The brand’s name suggests a copy-trading angle — following other punters’ bets — which is a different feature from a sportsbook menu and worth treating as such; it is a way to back other people’s tips for a fee, and the fee is in the price the tipster’s followers take.
The verdict: a working sportsbook with a racing-first focus. We suggest checking the site on the day of a BWF event to see if the market is active, and regarding the copy-trading feature, approach it as you would any tipster: treat the probability as an opinion, not a forecast.
BoyleSports
BoyleSports is operated by Boylesports Enterprise (Commission account 39469) under full UK regulatory compliance. The App Store listing carries the terms of the Acca Insurance offer: opt-in required, a minimum stake of £5, minimum odds of 1/2, a maximum refund of £20 as a free bet, the free bet expires in seven days, and the qualifying bets must be placed and settled on the same day. Those terms are the working example of what a UK-licensed acca insurance offer looks like under the 10x cap, and a punter who has not seen an acca insurance offer in writing should read them once, because the same shape — minimum stake, minimum odds, maximum refund, free bet with a seven-day expiry, settlement timing — recurs across the licensed market with small variations. None of it is a badminton offer.
The verdict: a licensed operator with a clean terms page and an acca insurance offer that is a fair example of the genre. For a badminton bettor the question is the same as for any of the bigger brands on this list: the menu is what the calendar is, and the offer is the offer the operator has decided to put in front of new accounts. BoyleSports is a working choice for a punter who already has the brand in mind; it is not a discovery for a punter looking for badminton depth.
BetTom
BetTom is run by Bet Tom Limited (Commission account 64959) and is fully authorized for UK customers. The App Store listing for the brand describes the sports welcome offer as 50% back as a free bet of up to £50, paired with a matching 50% back up to £50 as free slot funds for the casino. The “full terms apply” line is the honest gloss on any welcome offer, and a punter who has not read the small print has not read the offer. The 50% / £50 structure is a moderate welcome offer by the standards of the licensed market, neither the smallest nor the largest, and the casino pairing is the kind of mixed-product hook the 19 January 2026 ban was designed to cut back at licensed sites.
The verdict: a moderate welcome offer with the usual casino pairing, and a brand that a punter who likes the offer can take a £50 free bet from at a known cost. The cost is the wagering and the margin on the market the punter clears the bonus in, and the worked example above is the right shape of the answer.
Tote
Tote is the pool-betting brand of the British horse racing tradition, run by TDCO Limited (Commission account 54779) under official Commission oversight. The brand’s strongest offer is in pool betting on horse racing, where the dividend is set by the pool and not by a margin the bookmaker takes — a different product from a sportsbook margin. The badminton menu at Tote is whatever the operator’s sportsbook offers, and a punter who knows the brand for the Tote Jackpot is not looking at the brand for a badminton market.
The verdict: a pool-betting specialist with a sportsbook that relies on the calendar. For a badminton bettor, this brand is an occasional check rather than a primary destination.
Swifty Sports
Swifty Sports is operated by Swifty Global (UK) Ltd (Commission account 58957) and holds all necessary UK permits. The App Store listing offers Best Odds Guaranteed, Cash Out on selected markets including horse racing and football, daily price boosts, live streaming and in-play betting, with Bet Builder listed as coming soon. The features are the standard feature set of a UK-licensed sportsbook in 2026, and the “coming soon” tag on the bet builder is a useful honest signal: a brand that flags a feature as not yet live is a brand that has not yet claimed it has. The live streaming feature is worth checking on the day of a BWF event, because some events are streamed and the in-play market is usually offered alongside.
The verdict: a working mid-market sportsbook with the standard feature set and an honest tag on what is not yet there. A punter looking for a bet builder on the All England final should check the site on the morning of the match, as features evolve.
Fitzdares
Fitzdares is run by Fitzdares Limited (Commission account 400), an established operator with full UK regulatory credentials. The App Store listing describes the app’s offer as cash out, accumulators, Lucky 15s, specials and antepost markets on horse racing, football, tennis, rugby, cricket, golf and American football, with in-play live odds. Badminton does not appear among the listed sports, which is a useful signal of itself: a brand that markets its app around the sports it serves has, in this case, drawn the line at the bigger sports. A punter looking at Fitzdares for the All England Open should check the operator’s site on the day, not assume the menu from the App Store description.
The verdict: a premium-priced brand with a sports menu that does not list badminton among its headline sports. A punter who wants a deep badminton market should look elsewhere; those interested in the brand’s specials on major events will find what Fitzdares lists.
Betmaster
Betmaster is operated by BM Solutions GB Ltd (Commission account 65699), registered in Malta, and holds a full UK operator licence. The Malta registration is normal — several licensed UK sportsbooks are run by companies registered in other jurisdictions — and does not weaken the licence, because the Commission’s licensing point is the operator’s facilities used in Great Britain, not where the operator is incorporated. The brand’s badminton menu is not documented in the App Store listing this guide works from, and a punter who joins for the welcome offer should check the badminton menu on the operator’s site before the first bet.
The verdict: a licensed operator with a non-UK incorporation, which is normal for the licensed UK market. The brand is on the Commission’s register and is a member of GAMSTOP. Whether the menu meets the needs of an event is something the punter can verify directly on the operator’s site.
Bet600
Bet600 is operated by Tyche Tech Limited (Commission account 44731) with a valid GB operating permit. The App Store listing describes the brand’s headline offer as Best Odds Guaranteed on horse racing, paying at the starting price when the SP is higher than the price taken. As with Ladbrokes and Copybet, the headline offer is a racing offer, and a badminton bettor reading the App Store description is reading a racing-led page. The brand’s name — Bet600 — does not, on the listing, document a badminton-specific feature, and the badminton menu is whatever the operator offers that week.
The verdict: a licensed operator with a racing-led focus. This brand is a name on the register to keep in mind, though it is not a daily stop for BWF events.
bet365
bet365 is run by Hillside (UK Sports) ENC on a remote general betting standard (real events) licence; the Commission’s account number is 55148. The App Store listing describes in-play betting, live streaming of events worldwide, Bet Track, Match Live and a Live Golf Tracker for following bets in play. The live-streaming and in-play depth are the features that distinguish bet365 from most of the rest of the licensed UK market, and a badminton bettor looking at bet365 is looking at a brand that is more likely than most to offer a live stream of a BWF event and an in-play market to go with it. The wider margins on badminton in-play are the cost; the streaming and the in-play depth are the benefit.
The verdict: the operator with the deepest live-streaming and in-play offering on the licensed UK market, and the most credible place to look for a badminton in-play market at the bigger BWF events. The cost of the depth is the wider in-play margin, and the punter who takes the in-play price has paid for the streaming by the wider spread.
How to Use the Comparison
A reader who has read this far and is choosing where to place the first wager has three working questions to answer. The first is whether the brand is on the Commission’s register, which the table above confirms for each of the ten and which the Commission’s own register confirms for any other. The second is what the brand’s badminton menu looks like on the day, which the operator’s own sports page is the only honest source for. The third is what the offer costs to clear, which the wagering, the minimum odds and the deadline are the working inputs to, and which the margin on the market the punter plays is the multiplier that turns the wagering into a load.
The order the questions are asked in is the order the costs are paid in. The licence is free to check and pays for itself the first time a punter avoids a brand that is not on it; the menu is free to check, and pays for itself when the punter finds a brand that prices the match they want. The offer is paid for in turnover and margin, and the punter who has not done the arithmetic is the punter who pays the most for it.
Frequently Asked Questions
How do you bet on badminton?
Pick a licensed UK bookmaker from the Commission’s register, open and verify the account, browse the badminton section for the event and the market — match winner, handicap, total games or outright — and place the bet from your stake at the price shown. Settlement follows the operator’s market rules, which state what happens on a walkover, a retirement and a mid-match void. The verification step is not optional, and a brand that does not ask for it is not on the register.
What is a value bet, and why is no tip ever certain?
A value bet is a price whose implied probability is below the punter’s own estimate of the true probability of the outcome. A tip is a name attached to a probability, and the punter’s job is to estimate the probability and compare it to the price. Form, head-to-head and tournament round are inputs to the estimate. None of them is decisive, all of them are noisy, and the noise is what the bookmaker’s margin charges for.
What is the bookmaker’s margin and how can it be seen in the odds?
The margin is the cut the bookmaker takes from every unit bet on a market. On a two-way match winner at 1.90 and 1.90, the two implied probabilities (1 of 0.526) sum to 1.053, and the excess of 0.053 over 1.00 is the margin — about 5%. Real margins on badminton are wider than on football or horse racing because the market is thinner, and outright markets carry wider margins still.
How is the return on a bet worked out from the stake and the odds?
Return is the stake multiplied by the decimal odds. Profit is the stake multiplied by (odds − 1). A £10 stake at decimal odds 2.50 returns £25 and profits £15. For a combination bet the odds of the legs multiply into one price. For an each-way bet two equal stakes are placed, one on the win and one on the place, and the place part pays at the place terms stated by the operator.
How can it be checked that a bookmaker holds a Gambling Commission licence?
The Commission’s public register is searchable by business name, trading name, domain or account number. The register entry shows the licence categories and the operating company. A brand whose name is not on the register is not licensed to take bets from customers in Great Britain, and the absence of the register entry is the absence of the licence.
Which tools for controlling play does a licensed bookmaker have to offer?
A licensed remote operator offers deposit limits, time-outs, product restrictions and self-exclusion, and is a member of GAMSTOP, the national multi-operator self-exclusion scheme. The licensed operator must offer a frictionless route to GAMSTOP from the safer-gambling page, and the route is the test of whether the safer-gambling page is real or marketing. Help is also available from GamCare, GambleAware, the NHS gambling clinics and Gamblers Anonymous.
Tennis, darts & cue sports – Matchedbettinguk.com
Content created by the «Matchedbettinguk.com» team
